Opinion: Beyond fintech—the case for a Finternet
Finternet is neither a ‘blockchain of finance’ nor simply Fintech 2.0. It is a vision for a deeply interconnected financial architecture


By Dr Sukhamaya Swain, Dr Sana Maidulllah, Dr Charu Bansal
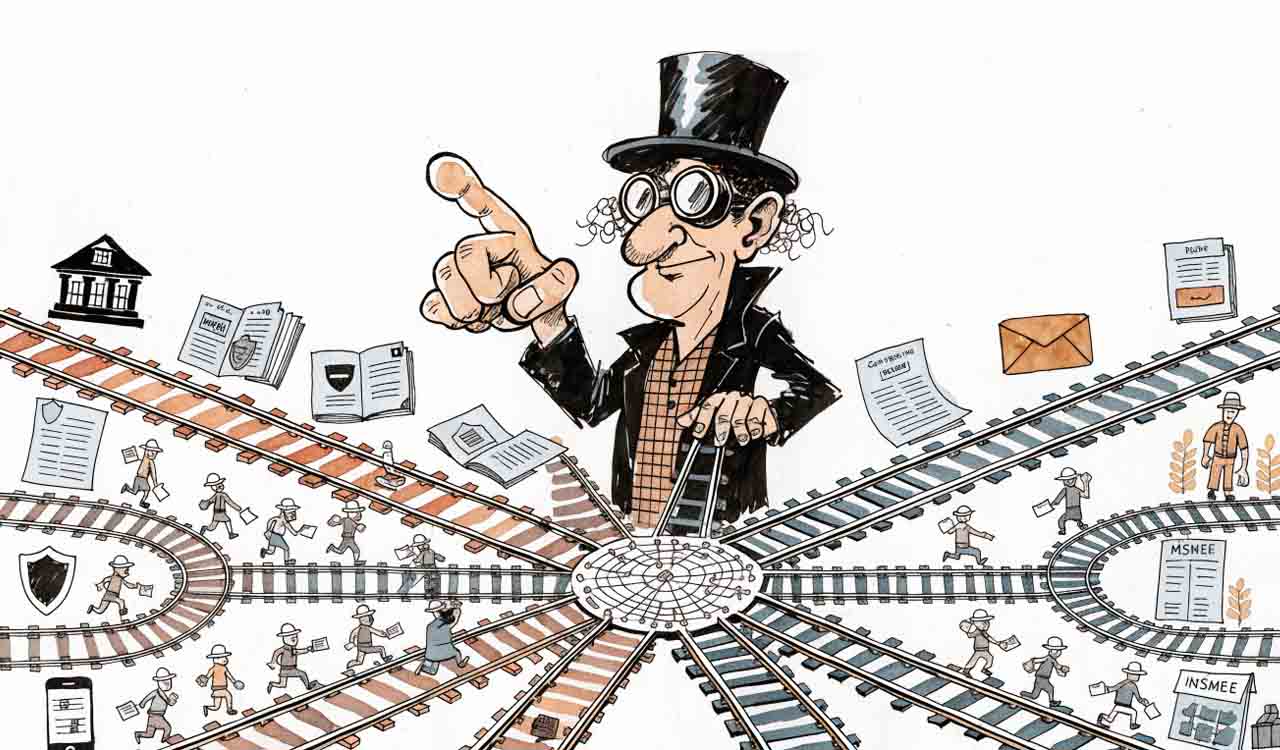
For decades, the internet has transformed how we communicate, travel, work and shop. Yet the most digital aspect of our lives—finance—remains fragmented, with a vintage architecture. A cross-border payment, loan disbursal, insurance claim or securities pledge may involve multiple databases, messaging systems, protocol checks, intermediaries, and clearing and settlement processes. What if finance could undergo a transformation like the internet, which has connected millions of separate and unrelated networks?
That is the core idea behind ‘Finternet’: a financial system that lets money flow across multiple intermediaries, along with the required data and adherence to the required protocols. The vision was conceptualised by Agustin Carstens of the Bank for International Settlements (BIS) and Nandan Nilekani in BIS Working Paper 1178 published in 2024.
Genesis of the Idea
Finternet is not synonymous with cryptocurrency, fintech, digital banking or digital currency. While fintech helps digitise or improve one or a set of financial services, Finternet addresses a more fundamental question: can the architecture connecting the multiple cohorts of financial services be redesigned?
Internet is the obvious inspiration. Just as the internet connects multiple networks through acceptable protocols, Finternet envisages the interconnectedness among various ecosystems such as banks, insurance, payment mechanisms, wallets, capital markets, development agencies, and governments. The BIS paper argues that much of the financial infrastructure remains fragmented despite rapid advances in technology.
For a layman, this can be understood through a simple example of being able to transfer, pledge or sell (fully or partially) a share, bond or an insurance claim like we do a transfer of money.
Tokenisation
India offers itself as a unique laboratory for advancing the Finternet. It already has a robust payment mechanism in the form of UPI, and we have seen a drastic change in consumer behaviour as a result. The full stack of digital payment infrastructure, ie, consent-based data sharing, digital documentation, e-signatures, Aadhaar-based identification, is present, and these need to be stitched together.
At the foundation is tokenisation, representing money and financial assets. A bond, share, bank deposit or any other financial asset can be digitally represented as a token.
But merely converting an asset into a token is not enough; it is the sewing of each of them to a unified platform; that’s the challenge! The BIS paper talks about a unified ledger.
Built on tokenisation, unified ledgers and digital infrastructure, Finternet could reshape payments, insurance, credit and capital markets
Take farming, for example. Crop insurance travels from the field to the insurer, to the government official and the banker, requiring a lot of paperwork and follow-up. Imagine a crop insurance payout happening seamlessly in the event of crop loss, enabled by relevant data points such as the farmer’s identity, crop details, weather information, credit details and insurance being appropriately linked.
Consider MSMEs, for that matter. An invoice could act as a digitally verifiable asset linked with the buyer’s credentials, bank account and credit history. A Finternet architecture could reduce the time between “raising an invoice” and “receiving capital”.
The government of India has many social schemes for the benefit of the masses, including subsidies, student scholarships, direct benefit transfers (DBT), maternity benefits, interest subvention, ex gratia payments and research grants, all of which could be brought into a programmable frame.
Municipal bonds, green bonds, InvITs, REITs, carbon credits, and renewable-energy assets could also be tokenised, ensuring smaller denominations, wider participation and transparency. In a country that is economically diverse and complex, the number of possible applications could be huge.
Finternet as a concept is not just a theoretical aspect. It has seen adoption in the form of Project Agora, where seven central banks and 40 financial institutions have developed a program for cross-border payments. The program intends to join tokenised central bank reserves with tokenised commercial deposits, smart-contract programmability and create a shared multi-currency ledger.
Initiated by BIS and the Institute of International Finance (IIF), it has seen real-value testing in July 2026 across 28 financial institutions across selected currencies totalling up to CHF 8,00,000.
Similarly, Project mBridge was a multi-central-bank digital currency initiative to facilitate faster and more transparent cross-border payments through a shared distributed ledger platform. The main aim of these experiments is not to replace banking but to reduce settlement, operational and reconciliation frictions.
The Challenges
With the benefits come the challenges. Strangely, most of the questions cannot be answered by technology alone. Issues such as legal ownership, settlement finality, jurisdiction, dispute recognition and resolution, cross-border recognition, accountability, adherence to anti-money laundering protocols, data privacy and protection could be impediments to the progress and adoption of Finternet.
Another dimension is trust, for which we need to have the following in place: verifiability, interoperability, scalability, security and privacy. Regulation has to evolve alongside technology. The legal and governance framework is equally critical to technology and economic architecture for the successful delivery of a Finternet package.
There is an economic dimension, too. What if the system becomes too complex to design and operate and therefore becomes expensive? Will there be takers? Will the institutions involved agree to share the cost? If the cost is passed on to users, will they be willing to bear it? The design must be user-centric, as the BIS paper also argues.
Thus, Finternet should not be treated as a ‘blockchain of finance’ or Fintech 2.0; it should be seen as a vision of strongly interconnected financial architecture. The internet changed communication because it did not digitise; rather, it changed the way networks interacted. Finternet is seeking to do the same for finance.
(Dr Sukhamaya Swain is Professor of Finance, Dr Sana Maidulllah is Assistant Professor of Marketing, and Dr Charu Bansal is Director, Finance and Banking, JK Business School, Gurugram)
Related News