The retirement plans of people whose jobs are disappearing
I have heard some version of that sentence too many times this year, from people in very different jobs, and it is not only anecdote. In the World Economic Forum’s latest survey of employers, 41 per cent said they expected to cut headcount where AI could take over the task.
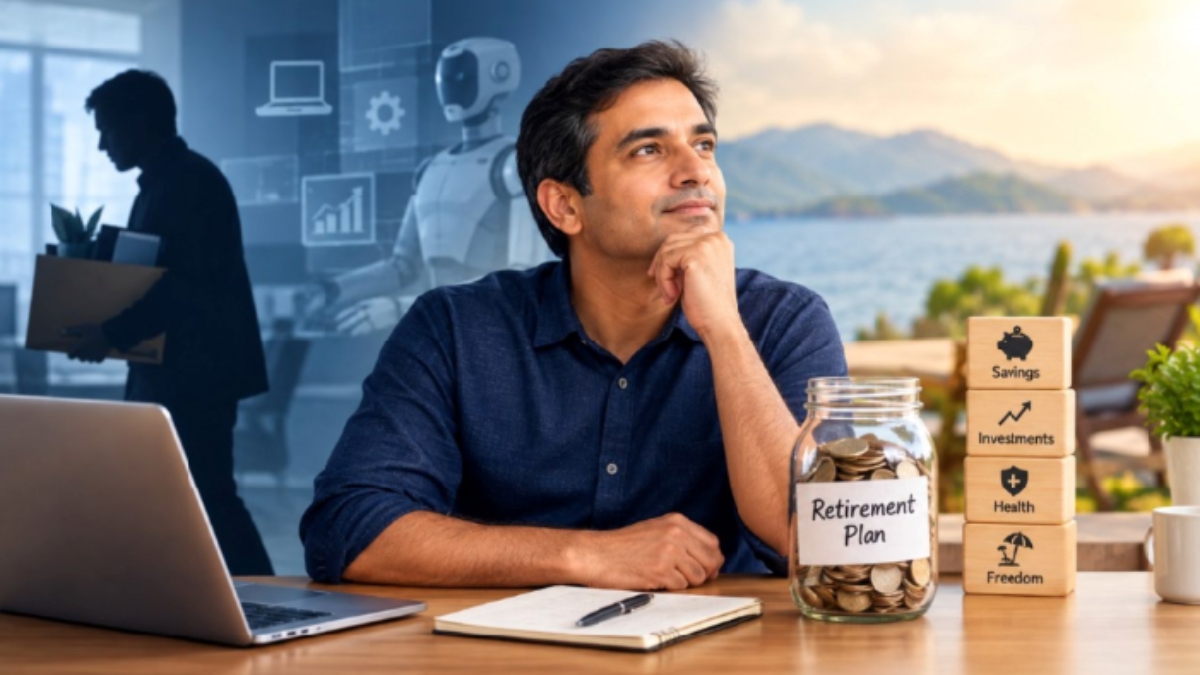


Venkat and I sat two desks apart at a bank in Chennai for four years in the late 2000s. He ran credit documentation, the team that reads a loan file before the money goes out and finds what is missing, and I ran a smaller, noisier team down the corridor. We became friends later, the way people from an old office do.
He turned 55 in January. That month he was told that the bank had spent two years training a system to read the files his team read, that it now did so faster and more accurately than 38 people could, and that the function was moving under technology. His role would close in March. The package was fourteen months, and fair.
“I kept waiting to feel wronged,” he said when I saw him in April. “I could not. They did it properly. And the truth is the system is good. I would have signed off on it myself.”
I have heard some version of that sentence too many times this year, from people in very different jobs, and it is not only anecdote. In the World Economic Forum’s latest survey of employers, 41 per cent said they expected to cut headcount where AI could take over the task. A June brief from Boston College’s retirement research centre found that since late 2022, American workers over 55 in AI-exposed jobs have been leaving them faster than before, mostly to look for work rather than to retire. Venkat sent me that one himself, with a line underneath: that was my team, and then it was me.
The busy months, and then the spreadsheet
He was busy through April and May. Two former bosses gave him advisory work, paid by the day. He was at the dining table by nine and told people he was exploring a few things. By July the advisory days were coming three or four times a month, and the rest of the week was harder to describe.
In August he opened his retirement plan. It is a spreadsheet he built in 2018, after a colleague’s father spent three weeks in ICU, a careful thing: a low return assumption, retirement at 60, a plan that runs to 75, because his father had gone at 71 and so had his uncles. He had opened it every Diwali and it had always said he was fine.
He changed the 60 to 55 and rang me.
He had expected the corpus to be about a sixth smaller. It was about a fifth smaller, roughly ₹3.4 crore in the illustrative version he showed me, because the five years he had lost were the five in which he would have saved the most. His salary had peaked. The home loan had closed in 2023 and his daughter’s fees the year after. Those were the years the plan had been built around.
And then the other side, which he had not looked at. Stop at 60 and plan to 75, and the money has to last 15 years. Stop at 55 and it has to last 20. He and his wife spend around ₹12 lakh a year, so that is roughly ₹60 lakh more, in today’s money, from a pot that had just got smaller. He checked it against a retirement calculator online in case his sheet was being unkind. It was not.
| Venkat’s spreadsheet, two versions | Income stops at 60 | Income stops at 55 |
| Years of earning left (from 50) | 10 | 5 |
| Approximate corpus at retirement | Base case | Roughly a fifth smaller, about ₹3.4 crore less |
| Years the corpus must fund (to 75) | 15 | 20 |
| Combined effect | Plan as designed | Smaller corpus, plus roughly ₹60 lakh more to fund in today’s money at ₹12 lakh a year |
“I stress-tested the returns, I stress-tested inflation,” he said. “I never stress-tested the date.”
I did not say the other thing, which is that 75 is his father’s number and his own is more likely to be 85, and a plan that stops at 75 does not know that either. It was not the day.
What I keep thinking
It is easy to make large arguments about AI, that it is bad for the planet, that it is doing something to our attention, and some of them are probably right. Sitting with Venkat, the argument that mattered was smaller and more certain. We are early in something whose shape nobody knows yet. What a job is, who does it and how long it lasts are being decided in rooms most of us are not in, and a lot of good people in their fifties are going to be the collateral of that deciding. None of it changes the fact that they will still need to eat, pay for hospitals, and live a long time after the last salary.
So the one question I now ask everyone I know is what date is in their plan. Most say 60, because that is what the provident fund says and nobody has told them otherwise. The labour market has already moved that date. The plan has to move with it, and it is better moved at the dining table than in a meeting.
Venkat’s says 58 now. He is 55, has not drawn a salary since March, and for the first time in twenty years his plan and his life are working from the same number.
Related News